Závěrečná práce: Munkh-Od Dashdondog: Applications of event study methodology for measuring of a market reaction
Diplomová práce
Applications of event study methodology for measuring of a market reaction
Anotace
This thesis aims to provide an empirical analysis of the market reaction from information about addition and deletion to/from the S&P 500 under an efficient market hypothesis. In that way, event study methodology is used to detect abnormal returns and three different test statistics: t-test, Patell Z test, and Generalized sign tests to check H0: AR=0 null hypothesis. Abnormal returns are defined as …více
Abstract
This thesis aims to provide an empirical analysis of the market reaction from information about addition and deletion to/from the S&P 500 under an efficient market hypothesis. In that way, event study methodology is used to detect abnormal returns and three different test statistics: t-test, Patell Z test, and Generalized sign tests to check H0: AR=0 null hypothesis. Abnormal returns are defined as …více
Zadání práce
The thesis aims to verify the applicability of event study methodology to measure a market reaction on a particular situation.
The process of work:
1. Introduction
2. Literature review focused on applicability of event study methodology on stock prices
3. Methodology and dataset introduction
4. Application of even study methodology on selected data
5. Analysis of findings and formulation of results
6. Conclusion
Methodology: analysis, comparison, deduction.
16. 5. 2021 11:13, Ing. Dagmar Vágnerová Linnertová, Ph.D., učo 76289
 angličtina
Literatura
- Handbook of econometrics. Edited by James J. Heckman - Edward E. Leamer. Amsterdam: Elsevier, 2007, xxviii, s. ISBN 9780444532008.
- BINDER, J. The Event Study Methodology Since 1969. Review of Quantitative Finance and Accounting. 1998, roč. 11, s. 111–137.
- KOTHARI, S. P. a J. B. WARNER. Handbook of Corporate Finance: Empirical Corporate Finance. North Holland, 2006.
- FISHER, Lawrence; Michael JENSEN a Richard ROLL. The Adjustment of Stock Prices to New Information. International economic review. Philadelphia: Economics Department of the University of Pennsylvania, 1969, č. 10, s. 1–21. ISSN 0020-6598.
Práce na příbuzné téma
Seznam prací, které mají shodná klíčová slova.
-
Influence of the Ukraine-Russian conflict on cryptocurrency markets
Ing. Vujadin Janković -
Indexové prémie
Ing. Michal Kuča -
Úroveň racionality v chování investorů
Marijan Crnkovič -
Analýza anomálií na kapitálovém trhu
Bc. Tomáš Kukla, učo 323286 -
Analysis of Calendar anomalies in National Stock Exchange of India "NSE"
Ing. Danial Hasan -
Vliv Twitter příspěvků vývojářů kryptoměn na hodnotu měn
Ing. Tereza Cejnková -
Vliv vybraných veřejných informací na tržní cenu akcie vybrané společnosti
Ing. Jakub Klimeš -
Výnosy při prímární veřejné nabídce akcií
Bc. Jan Edward Strumpf
Složky
Soubory
-
Přidání souboru
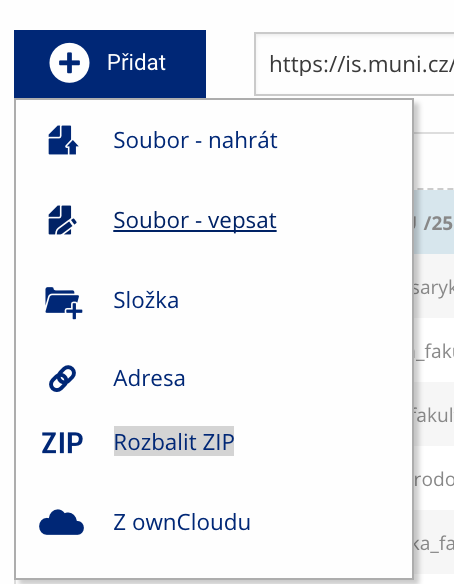 Soubor nebo složku lze nahrát pomocí tlačítka Přidat.
-
Další operace se soubory
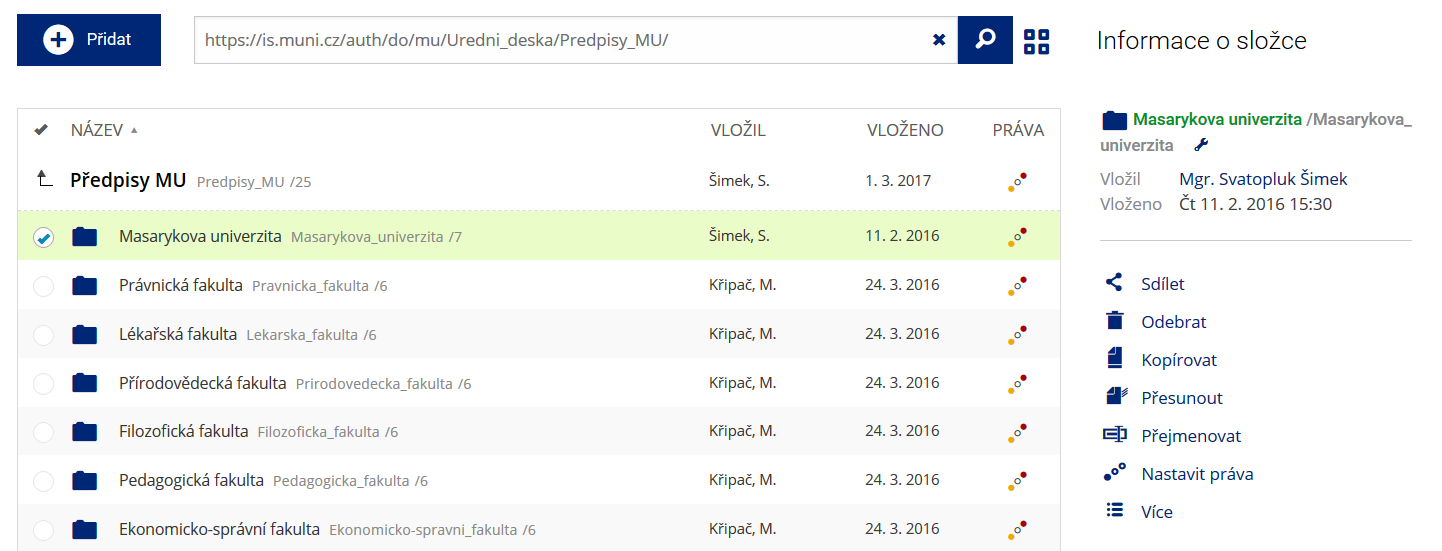 Podrobnosti lze zjistit označením příslušného řádku.
-
Pohled pro experty
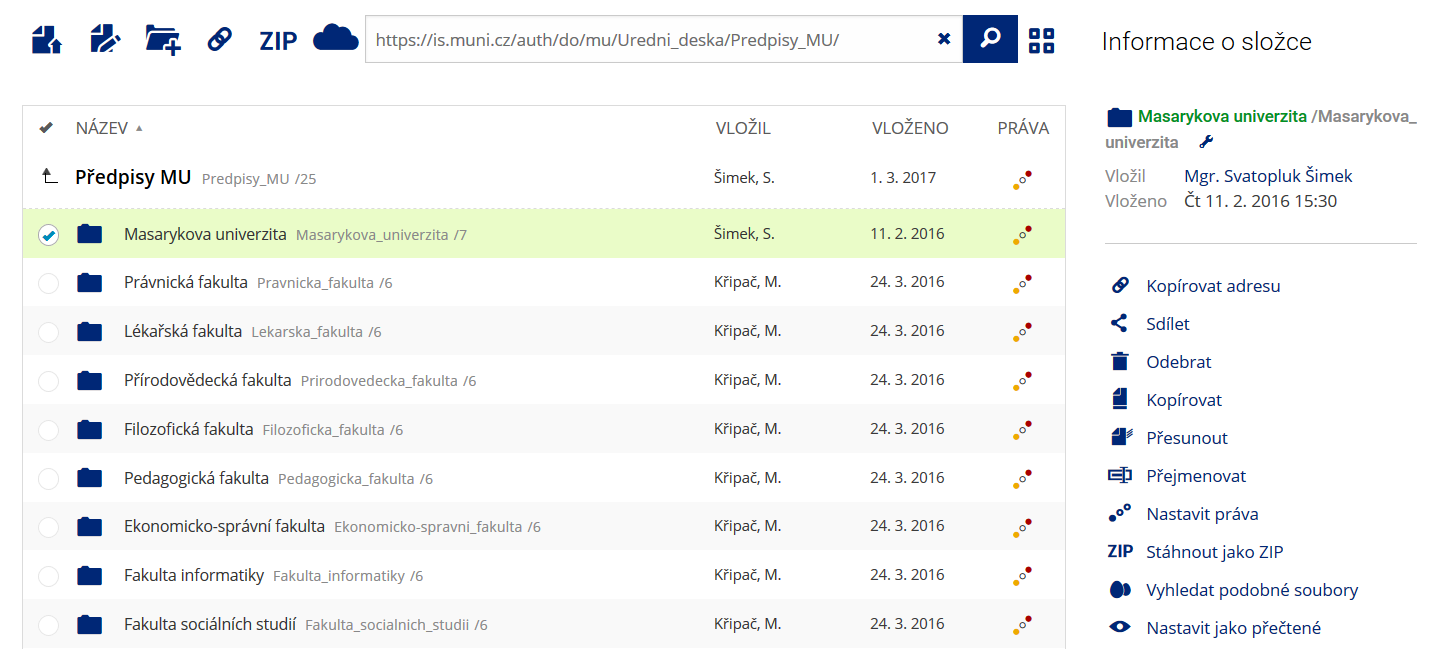 Pro častou práci je možné zvolit režim Více možností.
-
Vyhledávání souborů
 Vyhledávaný výraz můžete zadat přímo do adresního řádku.
-
Rychlý přístup k souborům
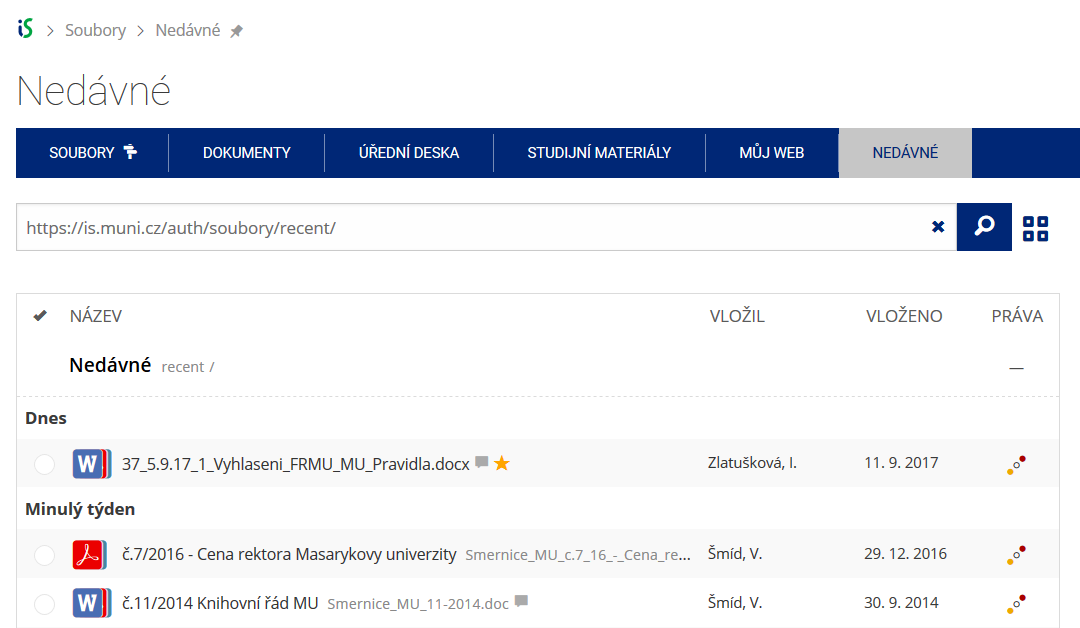 Pomocí funkce Nedávné je možné se rychle vrátit k právě prohlíženým souborům. Oblíbené soubory je také možné označit Hvězdičkou.