Závěrečná práce: Mgr. Ladislav Šmarda: FATCA – Tax reporting obligations of the Czech financial institutions
Diplomová práce
FATCA – Tax reporting obligations of the Czech financial institutions
Anotace
Diplomová práce je zaměřena na vymezení povinností Finančních institucí zřízených na území České republiky v souvislosti s daňovým zákonem Spojených Států Amerických nazývaných obecně jako FATCA. Autor práce vymezuje právní rámec fungování FATCA a následně identifikuje jednotlivé povinnosti Finančních Institucí a jejich případné nedostatky. V praktické části práce jsou aplikovány získané poznatky na …více
Abstract
This thesis focuses on identification of legal obligations for Czech Financial Institutions regarding the U.S. law commonly referred as FATCA. Author of the thesis describes the FATCA´s legal framework following with the description of the legal obligations and their weak spots. In the practical part of the thesis, the acquired knowledge is used on resolving practical case studies. This thesis aims …více
Zadání práce
11. 5. 2018 06:25, Ing. Petr Valouch, Ph.D., učo 11223
- Zadáno/změněno 22. 6. 2018 10:46, Bc. Eva Koudelková
- Záznam založen 3. 10. 2017 14:34, Iva Havlíčková
- Zveřejnit od 10. 5. 2018 14:55, Iva Havlíčková
- Práce převzata 10. 5. 2018 14:55, Iva Havlíčková
 angličtina
Literatura
- ANDREONI, James; Brian ERARD a Jonathan FEINSTEIN. Tax Compliance. Journal of Economic Literature. American Economic Association, 1998, 818-860.
- TORGLER, Benno. Tax compliance and tax morale : a theoretical and empirical analysis. Cheltenham, UK: Edward Elgar, 2007, x, 307. ISBN 9781845427207.
- TORGLER, B. Speaking to Theorists and Searching for Facts: Tax Morale and Tax Compliance in Experiments. JOURNAL OF ECONOMIC SURVEYS. MALDEN: WILEY-BLACKWELL, 2002, roč. 16, s. 657–683. ISSN 0950-0804. Dostupné z: https://doi.org/10.1111/1467-6419.00185.
- RADVAN, Michal a Dana ŠRAMKOVÁ. Tax Law Components to Provide Incentives for Investment. In Brown, Karen B. (Ed.). Taxation and Development - A Comparative Study. 1. vyd. Cham: Springer International Publishing, 2017, s. 107-122. ISBN 978-3-319-42155-1. Dostupné z: https://doi.org/10.1007/978-3-319-42157-5_6.
Práce na příbuzné téma
Seznam prací, které mají shodná klíčová slova.
-
Consumer Protection in Banking in the EU
Mgr. Tomáš Rozsypal -
Financování malých a středních podniků
Ing. Michal Navrátil -
Dohled finančních institucí v EU
Ing. Marian Husár, učo 169969 -
Ochrana spotřebitele na finančním trhu
JUDr. Ing. Eva Doležalová -
Procesní aspekty řešení úpadku bank
Mgr. Jaromír Slováček -
Balance sheet approach a finanční krize
Ing. Jakub Dobeš -
Legalizace výnosů z trestné činnosti jako zdroj financování mezinárodního terorismu
Bc. Marian Šigut -
Právní úprava dohlížených finančních institucí v České republice
Bc. Tomáš Pospíšil
Složky
Soubory
-
Přidání souboru
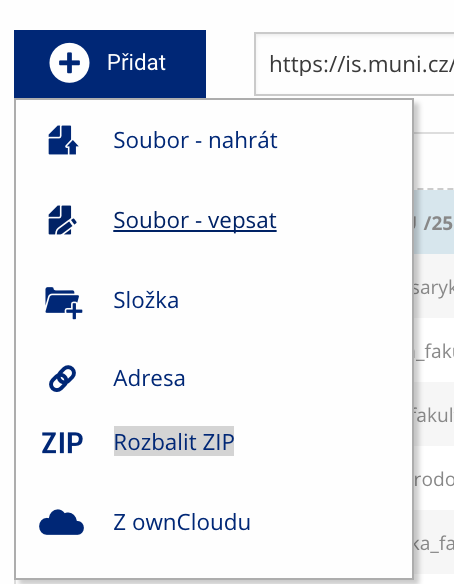 Soubor nebo složku lze nahrát pomocí tlačítka Přidat.
-
Další operace se soubory
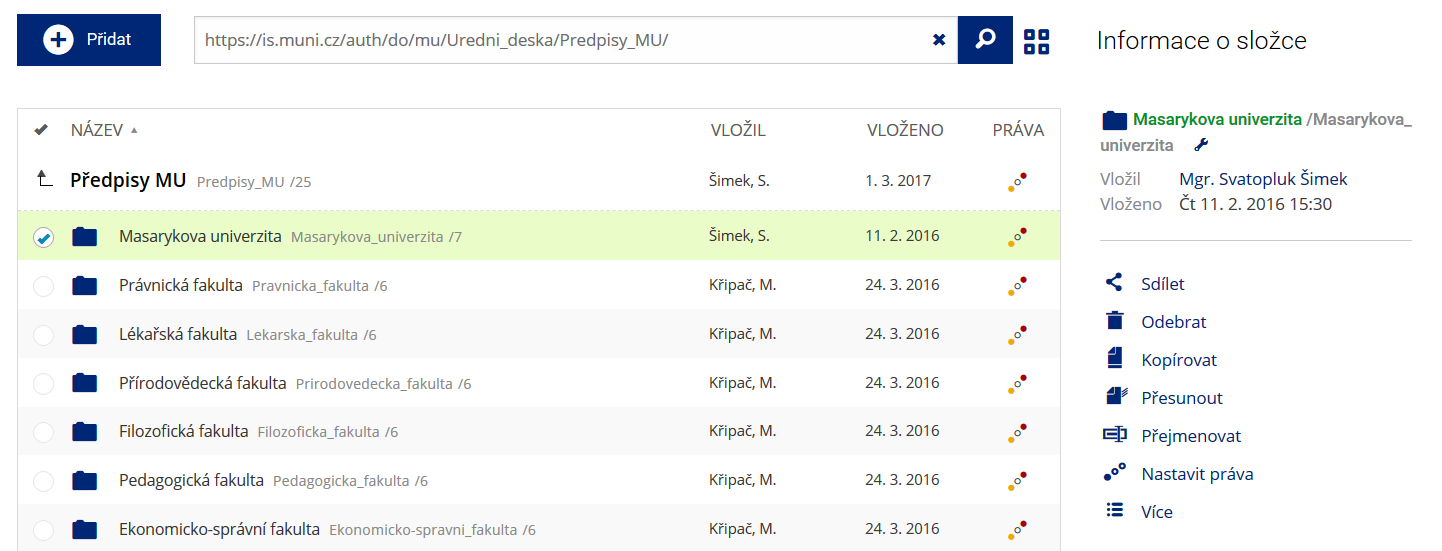 Podrobnosti lze zjistit označením příslušného řádku.
-
Pohled pro experty
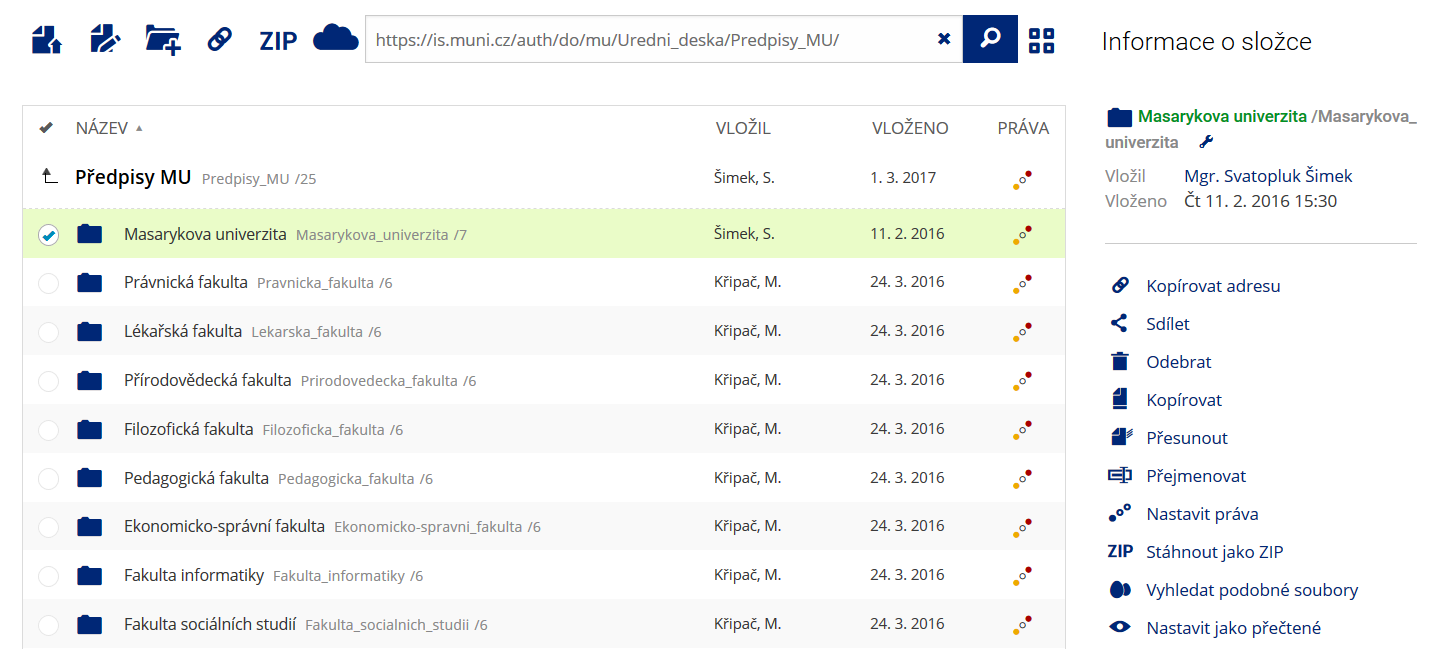 Pro častou práci je možné zvolit režim Více možností.
-
Vyhledávání souborů
 Vyhledávaný výraz můžete zadat přímo do adresního řádku.
-
Rychlý přístup k souborům
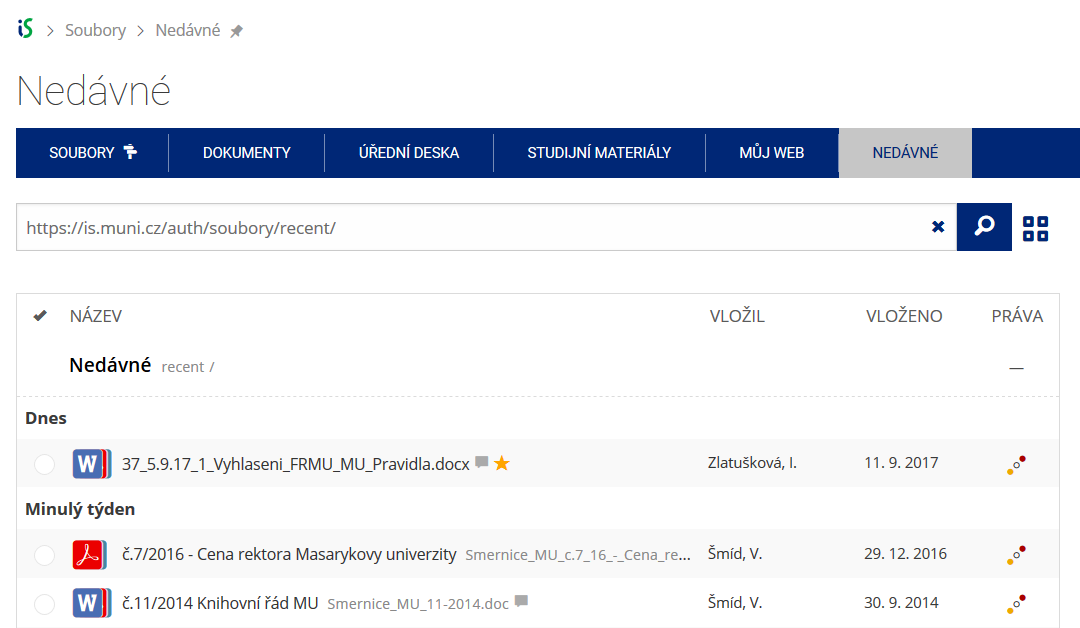 Pomocí funkce Nedávné je možné se rychle vrátit k právě prohlíženým souborům. Oblíbené soubory je také možné označit Hvězdičkou.